On a $3M Bay Area home, your buyer’s agent typically earns about $75,000, paid from your home’s sale price.
Agnsy’s operating system does the legwork, so our principal broker can focus on what actually decides your transaction. That efficiency allows you to purchase 3+ months sooner.
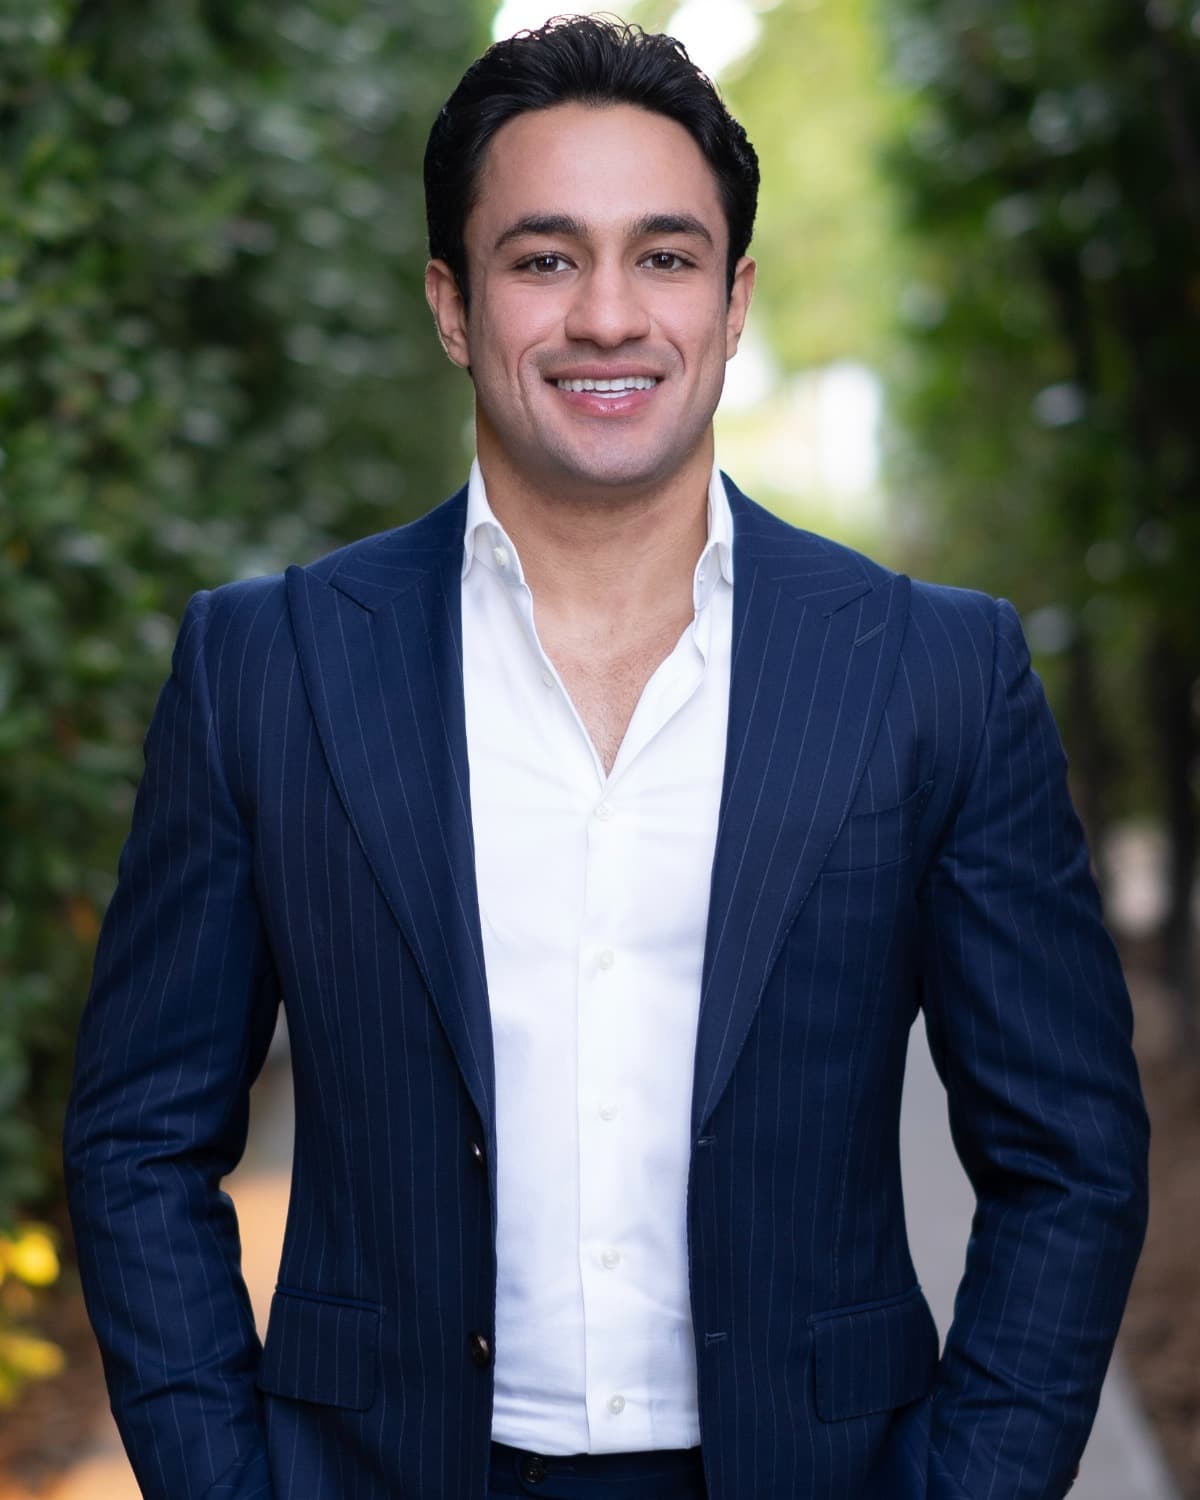
Kia Kalhori closed $22M in his first year and earned recognition as a Top 5% Agent at 19. After helping 100+ families, he left Compass to create an impact at scale. He is involved in every step of your transaction.
A 15-minute call with your broker to understand your goals and timeline.
Lender pre-approval with our vetted network and a cash plan that routes our credit where the loan permits. Or come pre-approved.
We begin recommending listings based on your criteria and provide access to our invite-only Atlas home search platform.
Disclosures, inspections, and comps are thoroughly reviewed so there are no surprises.
Once aligned on value, we strategize on offer terms to win without overpaying.
Escrow, appraisal, contingencies, lender are managed end-to-end. This is where you apply our credit.
Full credit applied to cash-to-close. They wired $34,000 less than they’d planned for.
Took the full credit as a cashier check at closing. $115,000 in hand the day they got the keys.
Same lender, same paperwork. The only change: her wire was $16,000 smaller.
Their lender approved the full credit toward cash-to-close. $27,944 stayed in their account.
Hybrid structure: covered closing costs, took the rest as a cashier check.
Can’t find yours? Book a 15-min broker call
Yes. We can coordinate with your lender so the sale-side proceeds, your financing, and the buy-side credit align. That means your closing dates can be synchronized, no double-move or bridge-finance. When our in-house mortgage operation ships, you’ll be able to run all three under one roof. Until then, we work with yours.
At closing. It either appears on your final closing disclosure as a reduction to cash-to-close, so you wire less money, or you receive a cashier check same day for the credit amount. Which path applies depends on your loan structure. Either way, the credit is yours at close.
In most cases the IRS treats a buyer-side commission credit as a price adjustment, not income. We are happy to coordinate with your CPA. Not to be treated as tax advice.
We retain 15% of the buyer-side commission. On a $3M home at a 2.5% buyer commission, that's $11,250, enough to run a small, tech-enabled, fiduciary team. We don't take referral fees, lender kickbacks, or vendor commissions, and have zero financial interest in steering you toward any service provider.
Bring them. Our capital plan works with any lender. We might lose the cash-to-close optimization depending on their guidelines, but the 85% credit is unaffected.
Discount brokerages cut commission by cutting service. Agnsy inverts the model. We retain top broker expertise from regionally ranked ex-Compass agents who earned the depth to know what can be automated and what shouldn't be while structuring financing around the credit. The 85% rebate isn't a margin cut. It's the residual after a software cost structure replaces a labor cost structure.
Listing agents see our offers as competitive offers, structured cleanly. Our credit is a buyer-side arrangement. It doesn't affect the seller's net or our presentation. We structure the offer to be seller-friendly and continue to win in multiple-offer situations against Compass, Sotheby's, and traditional brokerages.


